Full article
Published 21/09/2026
Table of Contents
- Key Takeaways
- The Doctrine of Limited Liability: Protection or False Security?
- Piercing the Corporate Veil: When the Shield Fails
- Personal Guarantees: The Most Common Trap for Irish Directors
- Reckless and Fraudulent Trading: High-Risk Behaviours Under the Companies Act
- Navigating Liability Risks with Specialist Legal Advice
- Taking Strategic Action to Safeguard Your Future
- Frequently Asked Questions
If your business is facing insolvency, you are likely asking one urgent question: am I personally liable for company debt in Ireland? For many directors, the assumption that a limited company acts as an absolute shield for personal assets like the family home is a dangerous misconception. While the principle of separate legal personality is the foundation of Irish corporate law, it isn't an impenetrable wall. If creditors or the Revenue Commissioners are applying pressure, the fear of losing everything you've built is both valid and overwhelming.
We understand the complexity of the Companies Act 2014 and the recent legislative shifts that have made it easier for liquidators to pursue directors. With this guide, you'll discover the specific scenarios where the "corporate veil" is pierced, including the new objective standards for reckless trading that remove the need to prove you acted "knowingly." By identifying whether your current behaviour puts you at risk, you can take proactive steps to safeguard your future. This guide explains the strategic path forward, highlighting how a €395 plus VAT consultation with a specialist barrister provides the expert legal advice needed to evaluate your personal exposure with precision.
Key Takeaways
- Understand the principle of separate legal personality and why limited liability is a robust, but not absolute, protection for directors.
- Identify the specific legal triggers that determine "am I personally liable for company debt in Ireland" under the Companies Act 2014.
- Recognise how personal guarantees create a contractual bypass of your company's limited status, often placing personal assets at risk regardless of corporate structure.
- Evaluate the dangers of reckless trading and the shift toward an objective legal standard where ignorance of the company's financial state is no longer a valid defence.
- Learn how to secure a strategic assessment of your position through a €395 plus VAT consultation with a specialist barrister to evaluate your personal exposure.
The Doctrine of Limited Liability: Protection or False Security?
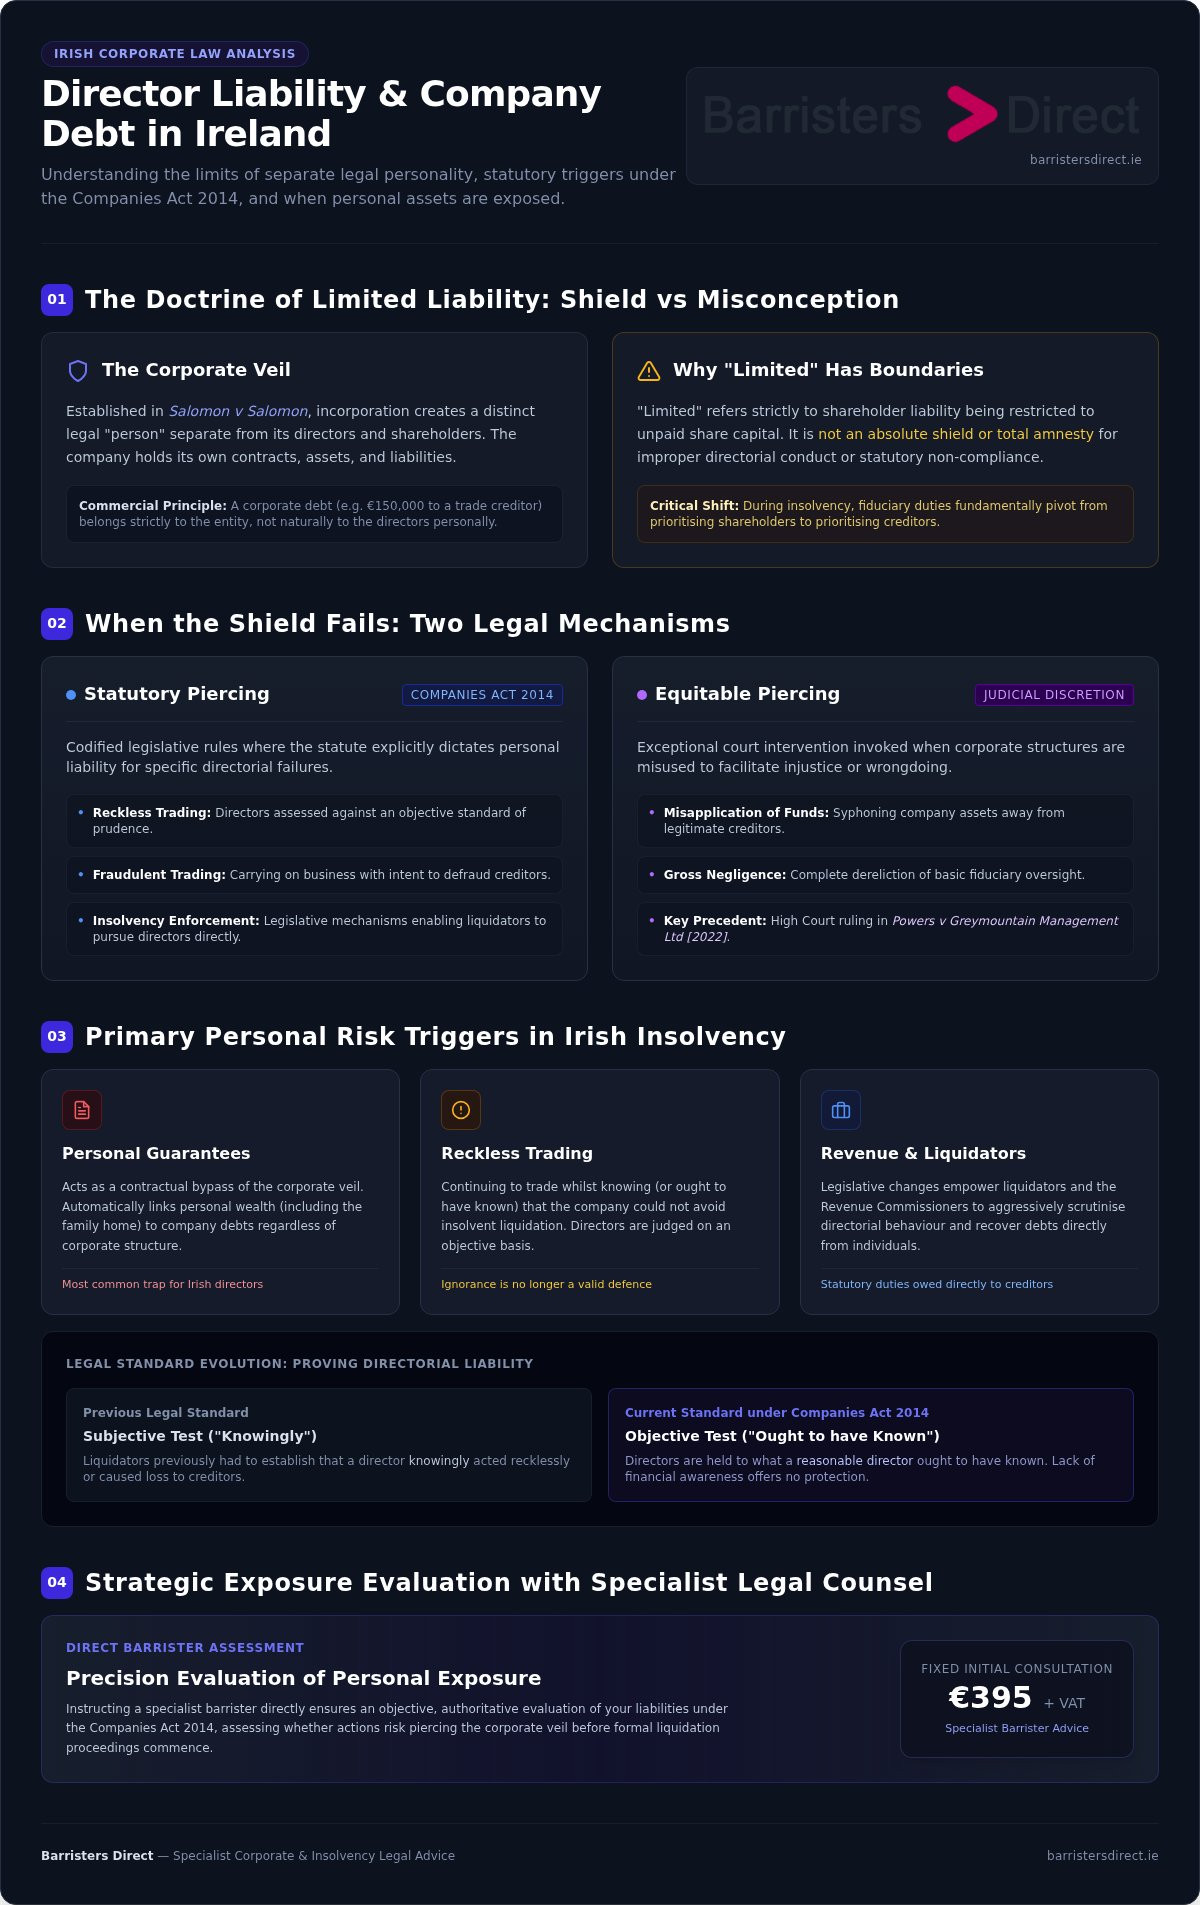
In Irish corporate law, the concept of separate legal personality is the bedrock of business. When you incorporate a company, you create a new legal "person" that is entirely distinct from its directors and shareholders. This entity has its own rights, enters its own contracts, and owns its own assets. The primary purpose of this structure is to encourage entrepreneurship by capping personal risk. It allows you to innovate and trade without the constant fear that a single business failure will lead to the loss of your family home or personal savings. If the business fails, the company's debts shouldn't naturally become your own.
However, many directors operate under the dangerous misconception that this protection is absolute. If you are asking "am I personally liable for company debt in Ireland", you must understand that limited liability is a shield, not an impenetrable wall. Legal professionals often refer to this boundary as the "corporate veil". It represents the line between the company’s obligations and your personal wealth. Whilst the law strives to keep this veil intact, there are specific legal mechanisms designed to pull it aside if a director's conduct falls below required standards.
The Corporate Veil in Irish Law
The landmark principle established in Salomon v Salomon remains the starting point for any Irish dispute regarding corporate debt. It confirms that a company is not an agent or trustee for its members; it is a separate entity. In a modern context, this means that if your company owes €150,000 to a trade creditor, that debt belongs to the company alone. Irish courts are traditionally reluctant to bypass this rule, as doing so undermines the stability of the commercial system.
Despite this reluctance, the protection is not a licence for impropriety. The process of piercing the corporate veil allows a court to set aside limited liability and hold individuals personally accountable. Recent jurisprudence, such as the High Court decision in Powers v Greymountain Management Ltd [2022], shows that the veil can be lifted in cases involving the misapplication of company funds or gross negligence. If the corporate structure is being used to facilitate fraud or to syphon assets away from creditors, the court will not hesitate to look behind the curtain.
Why "Limited" Does Not Mean "Unlimited" Protection
The word "limited" in a company name refers specifically to the fact that a shareholder's liability is restricted to the amount unpaid on their shares. It does not provide a total amnesty for a director's actions. While the company is a separate entity, you still carry significant fiduciary duties to act in the company’s best interests. If the company becomes insolvent, these duties shift, and you must prioritise the interests of your creditors over those of the shareholders.
If you breach these duties, the statutory protections you rely on can evaporate. Assessing whether your specific actions put your personal assets at risk requires a high level of specialist expertise. Identifying these risks early is the only way to ensure that "limited liability" remains a protection rather than a false sense of security.
Piercing the Corporate Veil: When the Shield Fails
While the corporate shield is robust, it isn't absolute. "Piercing the corporate veil" is a powerful legal remedy where a court decides to look past the company's separate personality to hold the individuals behind it accountable. In Ireland, this is an exceptional occurrence. Judges generally respect the corporate structure because it's essential for commercial certainty. However, if you're asking "am I personally liable for company debt", you need to understand the specific triggers that cause this shield to fail.
There are two main paths to personal responsibility: statutory piercing and equitable piercing. Statutory piercing occurs when the Companies Act 2014 specifically dictates that a director is liable for certain failures. Equitable piercing is a matter of court discretion, typically reserved for cases where the company structure is being abused to facilitate wrongdoing.
Fraud and Improper Conduct
If a director uses a company as a mere façade to conceal fraud or evade existing legal obligations, the court will likely pull back the veil. This often involves the deliberate misuse of company assets for personal gain or "phoenixing" a business to leave creditors behind. Improper conduct in this context requires a level of moral turpitude or gross impropriety that goes far beyond simple business failure or poor commercial judgment.
Statutory Exceptions Under the Companies Act 2014
The most frequent risks for Irish directors aren't based on court discretion but on specific legislative provisions. Section 599, for example, allows a court to order a related company to contribute to the debts of an insolvent one if it's just and equitable to do so. More critically for individuals, Section 610 of the Companies Act 2014 provides the primary basis for personal liability arising from reckless or fraudulent trading.
Directors can also face personal responsibility if the company failed to keep adequate accounting records, making it impossible for a liquidator to determine the true financial position. These rules ensure that the protection of limited liability remains tied to the responsibility of transparent and honest management.
Personal Guarantees: The Most Common Trap for Irish Directors
While the corporate veil acts as a default shield, a personal guarantee (PG) is a voluntary, contractual bypass of that protection. If you've signed a PG, the question of "am I personally liable for company debt Ireland" is usually answered by the terms of that specific document rather than general company law. By signing a guarantee, you've stepped outside the protection of the limited company and agreed to be personally responsible if the business fails to meet its obligations. This is the most common reason directors find their personal assets, including their homes, at risk during a liquidation.
Most guarantees include a "joint and several liability" clause. This means that if three directors sign a guarantee for a €100,000 loan, the bank isn't required to pursue each director for €33,333. Instead, they can choose to pursue any one director for the full €100,000.
Common Scenarios for Personal Guarantees
In the Irish market, personal guarantees are nearly ubiquitous for SMEs. Landlords typically demand them for commercial leases to ensure rent is paid even if the company is wound up. Similarly, banks and alternative lenders rarely provide overdrafts or term loans without a director’s guarantee. Perhaps more dangerous are trade credit applications; many suppliers include guarantee clauses in their standard terms and conditions.
Can a Personal Guarantee be Challenged?
Challenging a signed guarantee is notoriously difficult in Ireland. The courts place a high value on the "sanctity of contract," assuming that business people understand the implications of what they sign. To succeed, you must usually prove "undue influence" or "misrepresentation," which requires a very high evidentiary bar. Banks often mitigate this risk by insisting that directors receive independent legal advice before signing to ensure the agreement is enforceable.
Reckless and Fraudulent Trading: High-Risk Behaviours Under the Companies Act
If you are managing a company in financial distress, Section 610 of the Companies Act 2014 represents the primary statutory "danger zone". This provision allows the High Court to declare that any officer of the company is personally responsible, without limitation, for all or any part of the company's debts. When directors ask "am I personally liable for company debt Ireland", the answer often hinges on their conduct during the period leading up to insolvency.
The legal standard for reckless trading underwent a significant shift following the 2024 amendment to the Companies Act. The requirement that a director must have "knowingly" acted recklessly was removed, establishing a purely objective test. The court no longer focuses solely on what you actually knew; it examines what a reasonable director in your position ought to have known. If you continued to trade when it was clear that the company could not pay its debts, you may face unlimited personal liability regardless of your subjective intent.
What Constitutes Reckless Trading?
Reckless trading generally involves two specific types of behaviour. First, it includes carrying on business in a way that creates a substantial risk of serious loss to creditors, which a reasonable person should have foreseen. Second, it covers situations where a director contracts new debt without an honest and reasonable belief that the company would be able to repay it. Fraudulent trading is a higher bar, requiring proof of actual intent to deceive or defraud creditors, and can carry criminal sanctions.
There is a statutory defence available under Section 610. If the court is satisfied that a director acted honestly and responsibly, and took all reasonable steps to minimise the loss to creditors, it may grant relief from liability.
Consequences Beyond Financial Liability
The risks of reckless trading extend beyond your bank account. Under Section 682, liquidators are legally required to report director conduct to the Corporate Enforcement Authority (CEA). The CEA actively reviews these reports to decide whether to seek restriction orders under Section 819 or disqualification under Section 842.
Navigating Liability Risks with Specialist Legal Advice
Directors often wait until a liquidator is at the door before asking "am I personally liable for company debt Ireland". By that stage, the options for protection are often severely limited. Early intervention is the most effective way to identify high-risk behaviours and rectify them before they trigger statutory penalties or aggressive enforcement actions.
The Value of a Specialist Opinion
Specialist barristers provide an independent and objective review of your conduct as a director. Unlike internal stakeholders, a barrister offers a detached analysis of how a court would likely interpret your actions under the Companies Act 2014. This expert evaluation can prevent a potential dispute from escalating into full-blown High Court litigation.
Getting Started: Your Initial Consultation
The first step in securing your position is a preliminary legal evaluation. Barristers Direct facilitates direct access to specialist counsel through a transparent, fixed-fee model. For an initial consultation with a barrister, the fee is exactly €395 plus VAT. This session is designed to provide you with a clear understanding of your legal boundaries and any personal exposure you may face. If the matter is already contentious and involves other parties or potential court proceedings, a consultation where a solicitor also attends is available for €595 plus VAT.
Taking Strategic Action to Safeguard Your Future
The doctrine of limited liability provides a significant shield for Irish directors, but it isn't an impenetrable wall. As we have explored, the corporate veil can be pulled aside through contractual bypasses like personal guarantees or statutory triggers such as reckless trading under Section 610. If you're currently facing insolvency or creditor pressure, the question of am I personally liable for company debt Ireland requires a precise, expert answer based on your specific conduct and circumstances.
You can move from uncertainty to clarity by securing a specialist legal evaluation. Barristers Direct facilitates direct access to over 100 specialist barristers who provide the high-quality, objective advice needed to navigate these risks.
Frequently Asked Questions
Can a director be held personally liable for company debts in Ireland?
Yes, a director can be held personally liable under specific provisions of the Companies Act 2014. While limited liability is the default protection, this shield is removed if a director is found to have traded recklessly or fraudulently.
What does "piercing the corporate veil" mean in Irish law?
Piercing the corporate veil refers to a court's decision to bypass a company's separate legal personality to hold directors or shareholders personally accountable. Irish courts generally respect the corporate boundary to maintain commercial certainty, but will lift the veil if the company structure is used as a sham or a façade to facilitate fraud.
Is a director liable for the company's unpaid taxes to Revenue?
Directors are not automatically liable for a company's unpaid taxes, but they face significant risk during insolvency. If a liquidator determines that you allowed tax liabilities to accumulate whilst the company was insolvent and without a reasonable prospect of repayment, the court may impose personal liability.
What happens if I signed a personal guarantee and the company goes into liquidation?
Liquidation does not cancel a personal guarantee; it usually triggers its immediate enforcement. A guarantee is a private contract that exists independently of the company's limited liability status, meaning creditors can pursue your personal assets.
What is the difference between reckless trading and fraudulent trading?
Reckless trading is assessed using an objective test: would a reasonable director have foreseen that their actions created a substantial risk of serious loss to creditors? Fraudulent trading is a more serious allegation requiring proof of actual intent to deceive or defraud.
Can I be disqualified as a director if my company cannot pay its debts?
Yes, director disqualification is a common consequence of corporate insolvency. If your behaviour is found to be dishonest or irresponsible, the High Court may issue a restriction or disqualification order.
Does limited liability protect me if I am a sole trader?
No, sole traders do not benefit from limited liability because there is no separate legal entity between the individual and the business. You are personally responsible for all business debts and obligations.
How much does it cost to get a specialist legal opinion on director liability?
Barristers Direct facilitates consultations with specialist barristers for a transparent, fixed fee. An initial consultation costs €395 plus VAT, with a solicitor-attended option available for €595 plus VAT.
Disclaimer
_This article does not constitute legal advice. Barristers Direct does not provide legal advice. To obtain legal advice, you should contact a legal practitioner._